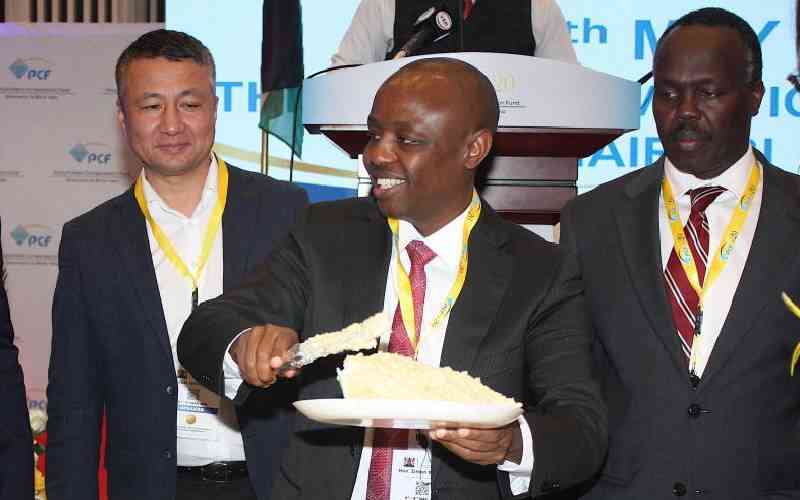
In a significant market stabilization move, the Policyholders Compensation Fund (PCF) has launched a comprehensive outreach initiative targeting customers affected by four collapsed insurers—BlueShield, United, Xplico, and Invesco Assurance.
This strategic intervention represents a crucial case study in industry risk management and regulatory effectiveness within Kenya’s evolving financial services sector.
The Fund’s “PCF Mtaani” campaign in Narok County reveals a deliberate shift toward proactive stakeholder engagement rather than traditional reactive compensation models.
This approach signals a sophisticated understanding of both market psychology and brand equity management within the insurance ecosystem.
“Our strategy centers on rebuilding market confidence through operational transparency,” explained Mamo Abudo, PCF’s Director of Corporate Services, highlighting how trust functions as an essential but intangible asset in financial services verticals.
The initiative addresses a critical market inefficiency—the KES 250,000 per claim ceiling currently provides liquidity to affected policyholders while preventing systemic risk from cascading through related financial networks.
From a business perspective, this calibrated intervention strikes a balance between moral hazard concerns and necessary consumer protection.
PCF’s regulatory innovation in 2019 merits particular attention from industry analysts. By successfully advocating for legislative amendments to the Insurance Act, the organization eliminated procedural bottlenecks that had created substantial time-to-value gaps in the compensation process.
This regulatory recalibration has transformed a previously sluggish claims settlement timeline into a responsive mechanism that better aligns with modern capital efficiency expectations.
The Fund’s disbursement of over Sh. 207.5 million to date represents not merely financial relief but a strategic investment in market stability. By mitigating consumer losses, PCF effectively preserves transaction confidence—a cornerstone of insurance market functionality.
Established in 2004 under the National Treasury and Economic Planning, PCF has evolved beyond its original mandate to become a sophisticated market stabilization instrument.
Its dual function of consumer protection and industry confidence-building illustrates how properly designed regulatory bodies can address both microeconomic concerns (individual policyholder protection) and macroeconomic objectives (sectoral stability) simultaneously.
This case exemplifies how targeted regulatory intervention, when strategically implemented, can strengthen market resilience while addressing specific business failures within Kenya’s developing insurance landscape.


Ray ID: 8f3a2c1b9d4e5f6a · Performance & security by Cloudflare
site-verification-ok